The moment the negotiating table freezes
Price talks have been going for a while when the founder says, with total conviction:
"Once next year's contract is signed, revenue doubles. You have to factor that into the price."
Across the table, the buyer nods, but their face tightens a little.
"We hope so too. But it isn't signed yet. Let's start from last year's numbers."
The room goes quiet in a strange way. The seller is looking at next year; the buyer is looking at last year. Same company, different time zones. This is where talks tend to stall.
Nobody said anything wrong. The seller's conviction is sincere and the buyer's doubt is reasonable. A common solution here is the earn-out.
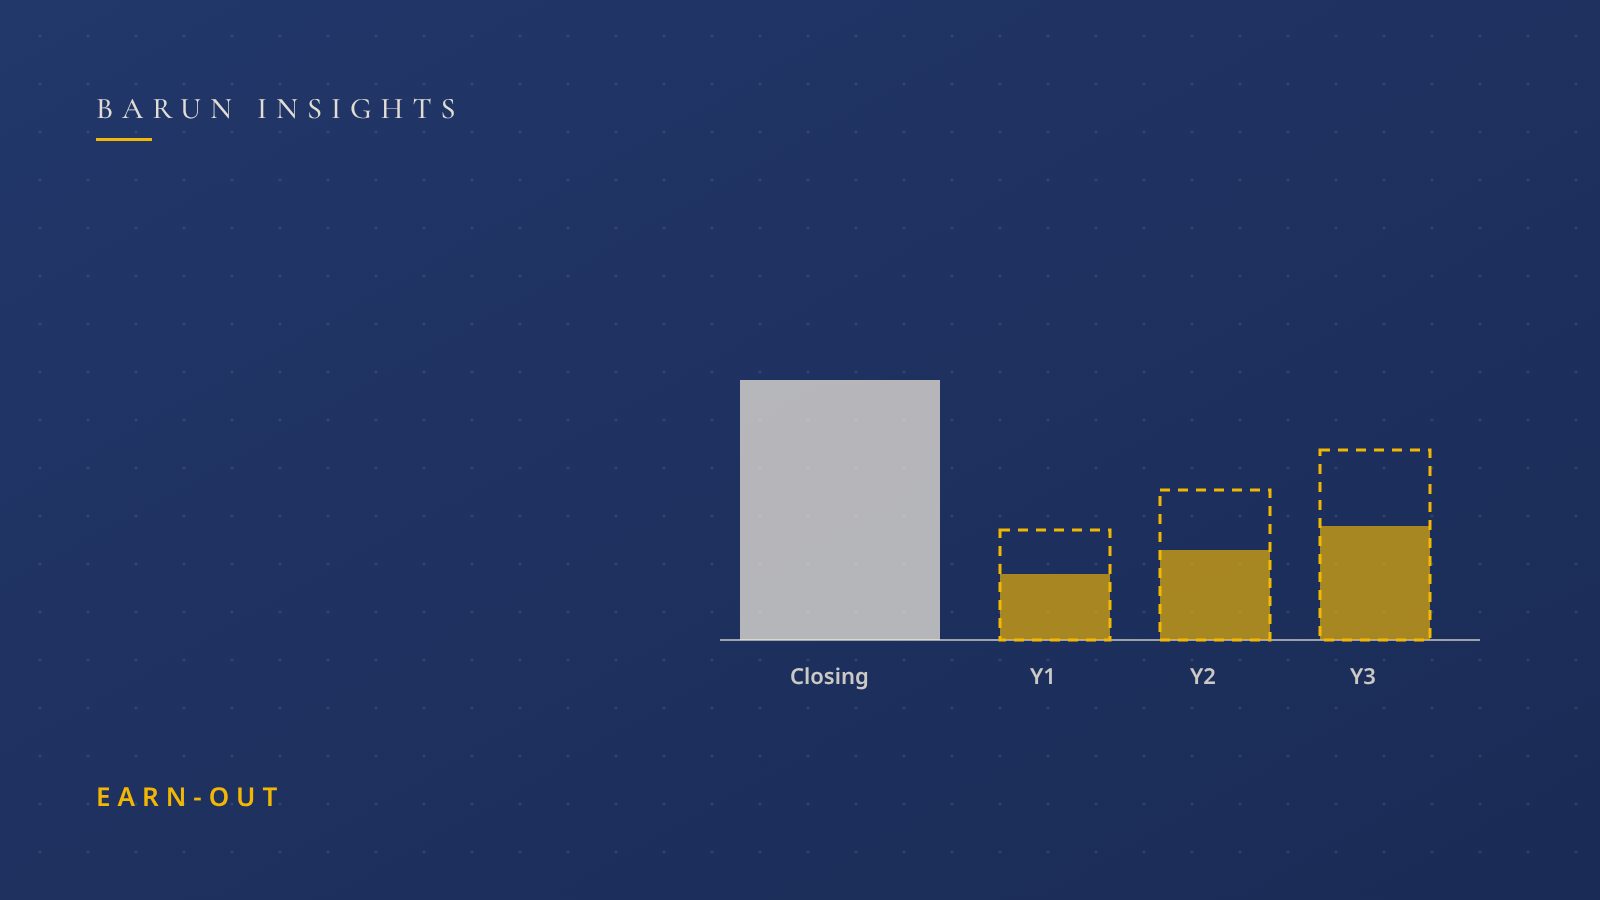
An earn-out is a simple promise: pay part of the price at closing and the rest according to performance over a set period afterwards. It says, "If you are so confident, prove it. If you do, we will pay you more."
An earn-out in one analogy
Think about buying a restaurant. The owner says, "Next month a big office building opens next door and lunch traffic will double." The buyer would love to believe that, but the building is still a construction site.
So they agree: "We pay today's price based on today's sales. If sales really grow that much in a year, we pay the difference." The seller bets on their own forecast, the buyer limits risk, and both sides check each other's claims against numbers.
When an earn-out fits
It is not always the answer. It works especially well when:
- Early-stage growth means history understates future value
- There is a near-term event such as a major contract or licence approval
- A founder stays on to run the business for a period
The third matters most. If the founder remains on the floor, "I am accountable for my own results" holds naturally. If the founder leaves right after closing, money rides on variables they cannot control, so be careful.
A hypothetical scene: Mr. Park's software company
Here is a hypothetical case. (This is not a real company. It is a blend of patterns we often see, and the numbers are purely illustrative.)
Mr. Park runs a B2B software company. Last year's revenue was 3 billion won. A big customer contract is nearly final, so he is certain next year will hit 6 billion. The buyer prices off last year's figure, which feels like a bargain-bin offer to Mr. Park.
They could agree something like this:
- Part of the base price is paid at closing
- Additional payments follow if targets are met over the next two years
- Targets pay out in tiers by percentage achieved, not all-or-nothing
Mr. Park, confident, would welcome it. But the real story starts here. Without metric definitions in the contract, this happens:
- After closing, the buyer allocates head-office costs to Mr. Park's company, and operating profit shrinks.
- Intra-group pricing with another buyer subsidiary changes and profit moves.
- The buyer merges his sales team into another unit, and the company's own results can no longer be isolated.
The target is missed, and Mr. Park says, "That wasn't my doing." This is the classic route by which an earn-out becomes a seed of disputes. Settling the five points below before signing prevents most of it.
Five things to define
1. Metric: revenue or operating profit
First: what is being measured?
- Revenue is harder to manipulate and suits the seller.
- Operating profit or EBITDA reflects profitability and suits the buyer.
Revenue is simple and visible, so it breeds fewer fights, but buyers worry: "Couldn't they hit the target by growing sales at a loss?" Operating profit reflects profitability, but many more variables can influence the calculation.
If profit is used, the contract must address these three things:
- How head-office cost allocations by the acquirer are treated
- How intra-group pricing is treated
- How accounting policy changes are adjusted for
"They'll calculate it sensibly" is the first sentence to collapse when a dispute starts.
2. Period and tiers
Usually one to three years. Too short, and a one-off number decides everything. Too long, and the post-closing environment shifts so much that the seller loses control of the outcome.
Tiers matter too. With all-or-nothing hurdles, hitting 99% of target pays zero, which feels deeply unfair. Pro-rata payments against targets cause fewer disputes.
For example, achieving 80% of the target pays a proportional amount. A table showing how much is paid at each level lets both sides negotiate off the same numbers.
3. Post-closing operating covenants
For sellers, this may be the most important clause.
The earn-out says you are paid based on post-closing results. But after closing, the buyer runs the company. If the buyer merges the sales team or discontinues a product, the target becomes impossible. That can happen from perfectly reasonable management decisions, with no bad faith at all.
So sellers should ask for protections such as:
- Separate P&L tracking for the business
- Retained key staff and budget
- No change of business without good reason
Of course the buyer cannot give up control entirely. This clause should be a joint exercise in deciding where protection ends and freedom begins. The key is to have that conversation before signing. After closing, it is too late.
4. Measurement and dispute procedure
Who calculates the numbers? That one question decides a surprising number of lawsuits.
Settle in advance:
- Who prepares the earn-out figures
- Whether the seller can inspect the books
- Which accounting firm decides if the parties disagree
Naming the firm, or agreeing how it will be chosen, keeps many earn-outs out of court. When two sets of numbers disagree, a rule already exists for who is right. Start without one and it becomes the nastiest fight after the deal.
5. Acceleration events
The last one is a safety net: if the buyer resells the business or breaches the agreement, the remaining earn-out becomes payable immediately.
It makes sense. The seller agreed to an earn-out on the premise that this buyer would keep running the company. If the buyer flips it a few months later, the premise collapses. An acceleration clause lets the seller collect the remainder at once.
Tax and accounting matter too
Depending on timing and character, earn-out payments can change tax treatment, for example:
- When the seller's gain is recognised
- Whether part is treated as employment income
Be especially careful where the founder keeps working after closing. The same money can be taxed differently depending on whether it is the price for selling the company or pay for work done. Review the structure with a tax adviser before drafting the contract.
The five at a glance
| Term | What to settle | What happens if you skip it |
|---|---|---|
| Metric | Revenue or operating profit/EBITDA; head-office costs, intra-group pricing, accounting policy | Same results, two different calculations |
| Period and tiers | Usually 1 to 3 years, pro-rata payment | Zero payout when you are near target |
| Operating covenants | Separate P&L, key staff and budget, no change of business | Buyer decisions make the target impossible |
| Measurement | Who calculates, book access, deciding firm | Disputes that end up in court |
| Acceleration | Immediate payment on resale or breach | Premise collapses but payment stays locked |
A few frequent questions
Q. Isn't an earn-out bad for the seller? Not necessarily. When the buyer offers a price based only on last year's numbers, an earn-out gives the seller a way to get growth potential into the price. It only works if the five points above are properly written into the contract.
Q. Must the founder stay during the earn-out period? Not necessarily, but the structure fits especially well when the founder stays on for a period. A departing founder has money riding on things they cannot control, so operating covenants matter even more.
Q. If we miss the target, do we really get nothing? That depends on the design. All-or-nothing can mean that; a tiered structure pays something in proportion to what was achieved. That is why tiers tend to reduce disputes.
Q. Is the earn-out taxed? Treatment can vary with timing and character. The timing of gain recognition and whether any part counts as employment income can both be issues, so review the structure with a tax adviser before signing.
30-second self-check: any blanks in your earn-out?
- ☐ The metric is clearly revenue or operating profit (EBITDA)
- ☐ If profit, head-office cost allocation, intra-group pricing and accounting policy changes are addressed
- ☐ The period is set within one to three years, with tiers by percentage achieved
- ☐ Covenants cover separate P&L, retained key staff and budget, and no change of business without good reason
- ☐ The contract says who calculates, whether the seller can inspect the books, and which accounting firm decides disputes
- ☐ The remaining amount is payable immediately on resale or breach
- ☐ A tax adviser has reviewed timing and character of payments
A first step you can take now
If you are convinced revenue will double next year, practise turning that conviction from words into numbers and contract sentences. Writing down which metric, how many years and what tiers is enough to make your negotiating position noticeably firmer.
An earn-out easily becomes "let's agree now and argue later". That is exactly why every line matters, and why it can feel daunting to draft alone. At Barun Investment we help design the structure and negotiate metrics and operating terms with the buyer, alongside tax and legal partners. A casual coffee and "how should we shape our earn-out?" is plenty to start.
Earn-outs easily become a way of saying "let's agree now and argue later". Defining every number in the contract protects both sides.
Considering a transaction? Start with a conversation
Talk to usThese notes are general and are not advice on any specific transaction.